Quick Answer: The Medicare Annual Enrollment Period (AEP) runs October 15 through December 7 every year, and the actual process comes down to five steps: review your Annual Notice of Change letter, list your current doctors and medications, compare plans using Medicare’s Plan Finder tool, check formularies and networks against your specific needs, and enroll online, by phone, or through a licensed agent before the deadline. Changes take effect January 1.
Knowing that the Medicare Annual Enrollment Period exists is one thing. Knowing what to actually do with it is another. Every fall, a lot of people let this window pass simply because the process feels vague, not because they don’t care about their coverage.
It isn’t actually complicated once you break it into steps. Below, I’ll walk through exactly what to do, in order, from the moment your Annual Notice of Change letter arrives to the moment you submit your enrollment. For the full rundown of this year’s dates and deadlines, see our companion post on Medicare Open Enrollment 2026.
Step 1: Read Your Annual Notice of Change Letter
Every plan sends its members an Annual Notice of Change (ANOC) letter by September 30, outlining exactly what’s different about the plan for the coming year, including premium, deductible, copay, and formulary changes. This letter is your starting point, not paperwork to set aside.
Read it against a simple question: does anything in here change what I actually pay or what’s covered? A premium increase, a drug moving to a higher tier, or a doctor leaving the network are all reasons to actively compare your options rather than letting your plan renew automatically.
A Trade-Off Worth Understanding
Skipping this step doesn’t cost you anything today. The cost shows up later, quietly, the first time you fill a prescription at a new, higher copay or discover a specialist you’ve seen for years is suddenly out-of-network. The ANOC letter is the cheapest, fastest way to avoid that surprise.
Step 2: List Your Doctors, Pharmacies, and Medications
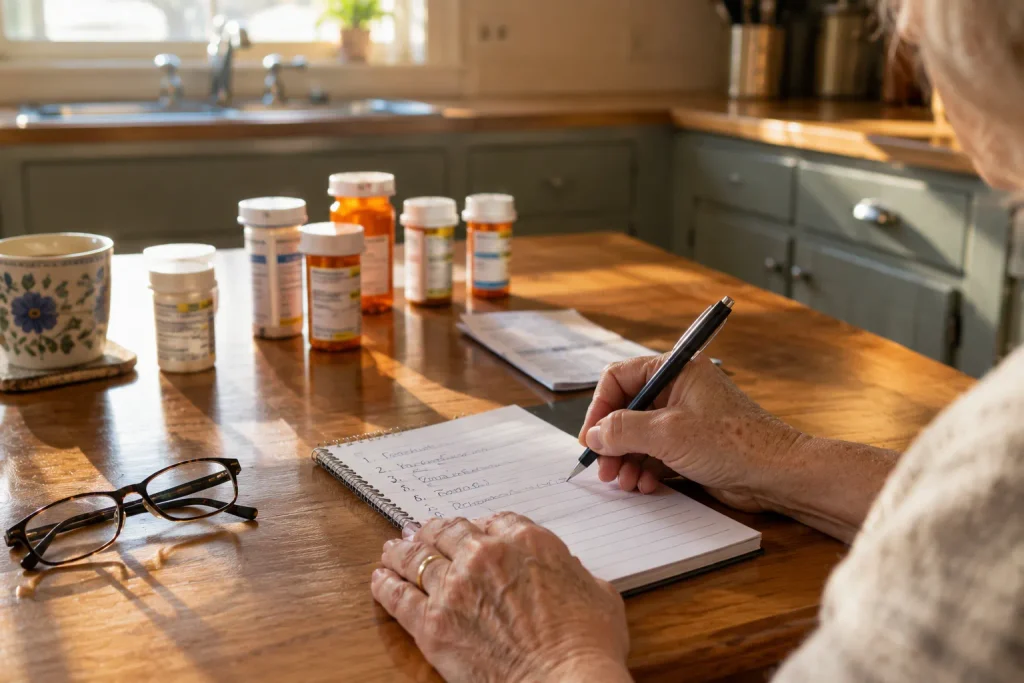
Before comparing a single plan, write down your current doctors, your preferred pharmacy, and every medication you take, including dosage and frequency. This list is what actually determines which plan fits you, far more than premium alone.
Without this list, you’re comparing plans in the abstract. With it, you’re comparing plans against your real life, which is the only comparison that actually matters.
Step 3: Compare Plans Using Medicare’s Plan Finder
Medicare’s online Plan Finder tool at Medicare.gov lets you enter your ZIP code, your medications, and your preferred pharmacies, then returns Medicare Advantage and Part D plans available in your area with estimated costs based on what you entered. You can also review each plan’s star rating, a 1-to-5 scale Medicare assigns based on quality and member satisfaction.
In 2026, most states have 8 to 12 standalone Part D plans available, and Medicare Advantage enrollees have access to an average of 32 plans that include drug coverage. That’s a lot of options, which is exactly why narrowing by your actual medications and doctors first matters.
A Real Scenario Worth Considering
Say you’re in Tulsa comparing Part D plans and two options look similar on premium alone. Plugging your actual medications into the Plan Finder might reveal that one plan puts your maintenance drug on a lower-cost tier, while the other requires prior authorization for the same drug. That difference wouldn’t show up anywhere except in a comparison built around your specific list.
Step 4: Check Formularies, Networks, and Total Costs
Once you’ve narrowed your options, go a level deeper on each one. Confirm your specific medications are on the plan’s formulary and note which tier they fall into, since that determines your copay or coinsurance. Confirm your doctors and hospitals are in-network if you’re considering Medicare Advantage. And look at total estimated annual cost, not just the monthly premium, since a low premium can still mean a higher total if cost-sharing is heavier.
If you’re on a Medicare Advantage plan and considering a standalone Part D plan instead, be careful here: enrolling in a standalone Part D plan while still in a Medicare Advantage plan can unintentionally cancel your Advantage coverage. This is exactly the kind of detail worth double-checking with a licensed agent rather than guessing.
Step 5: Enroll Before December 7
Once you’ve landed on a plan, you can enroll online through Medicare’s Plan Finder, by calling 1-800-MEDICARE, directly through the plan’s website or phone line, or with help from a licensed agent. You’ll generally need your Medicare number and your Part A and Part B effective dates on hand.
You can make changes as many times as you want during AEP; only your last submission before December 7 takes effect, and it applies starting January 1. If you’re happy with your current plan after reviewing it, you don’t have to do anything at all; it will simply continue.
What Happens After You Enroll?
You’ll receive confirmation from your new plan, along with a new member ID card before your coverage starts January 1. Keep your old plan’s card until your new coverage is confirmed active, just in case you need to reference it during the transition.
What If You Need Help Working Through These Steps?
Comparing plans against your actual medications, doctors, and expected costs takes real time to do well, and it’s easy to get it wrong when you’re working from premiums alone. This is exactly the kind of process I walk clients across the Tulsa area through every AEP, turning a confusing list of options into one clear recommendation.
If you’d rather not run the Plan Finder comparisons yourself, bring your medication and doctor list to a consultation and we’ll do the comparison together. You can schedule a free consultation and we’ll get you enrolled before the December 7 deadline.
Frequently Asked Questions
What are the steps to use Medicare’s Annual Enrollment Period?
Review your Annual Notice of Change letter, list your doctors and medications, compare plans using Medicare’s Plan Finder, check formularies and networks against your needs, then enroll online, by phone, or through an agent before December 7.
What is Medicare’s Plan Finder tool?
Plan Finder is Medicare’s official online comparison tool at Medicare.gov. You enter your ZIP code, medications, and pharmacies, and it returns available Medicare Advantage and Part D plans with estimated costs and star ratings.
Can I switch from Medicare Advantage to a standalone Part D plan during AEP?
Yes, but be careful: enrolling directly in a standalone Part D plan while still on a Medicare Advantage plan can unintentionally cancel your Advantage coverage. It’s worth confirming the right order of steps with a licensed agent.
Do I have to do anything if I like my current Medicare plan?
No. If you don’t make any changes, your current plan will continue automatically. It’s still worth reviewing your Annual Notice of Change letter first, since the plan itself may have changed even if you haven’t.
How many times can I change my plan during AEP?
As many times as you want. Only your final submission before the December 7 deadline takes effect, and it starts January 1.
The Bottom Line
The Medicare Annual Enrollment Period only feels complicated from the outside. Broken into steps, reading your ANOC letter, listing your doctors and medications, comparing plans against that list, checking the details, and enrolling before December 7, it’s a process almost anyone can work through in an afternoon.
If you’d rather have a second set of eyes on the comparison, call 918-815-6382 or schedule a free consultation and we’ll get you enrolled before the deadline. For this year’s specific dates, see our Medicare Open Enrollment 2026 post, or browse our Medicare frequently asked questions for more detail.